Finance
Why Banks Offer Cash Signup Bonuses and What the Catch Is
Banks offer cash signup bonuses as acquisition spending, betting your deposits stay for decades. Learn the key requirements, taxes,
 Monday, October 12, 2026
The latest finance explainers on Rive News: sourced, human-written guides. Browse topics or read the newest stories below.
A 401k employer match is extra pay tied to your savings rate. Learn the common 50%-up-to-6% formula, 2026 IRS contribution limits, and vesting schedules.
Banks offer cash signup bonuses as acquisition spending, betting your deposits stay for decades. Learn the key requirements, taxes,
A credit freeze blocks lenders from seeing your credit report. Learn how freezes work, when to place one, and how to lift a freeze at all
Hard inquiries can cost a few points; soft inquiries never do. Learn the difference between the two, which checks are which, and how
An emergency fund is cash for job loss or surprise bills, sized at 3 to 6 months of essentials. Experts explain how to size your fund
Your 401k does not vanish when you quit. Compare the four options after leaving, learn the $7,000 force-out rule, and see why cashing out
A money market account blends savings interest with checking-style debit-card access. See how it compares to savings accounts on rates
Roth and traditional IRAs differ in one key way: when you pay taxes. This plain guide covers 2026 limits, income rules, withdrawals,
Indigenous Peoples Day 2026 falls on Monday, October 12. The stock market is open, but most banks and USPS are closed. See the full
A Motley Fool report warns the Shiller P/E nears a 156-year record at 41.67, and 74% of Americans expect a correction, according
Balance transfer fees run 3% to 5% of the debt you move, added to your balance on day one. On $5,000 that is $150 to $250, before interest
If your bank fails, FDIC insurance protects deposits up to $250,000 per depositor per bank, usually paid by the next business day. Here
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step
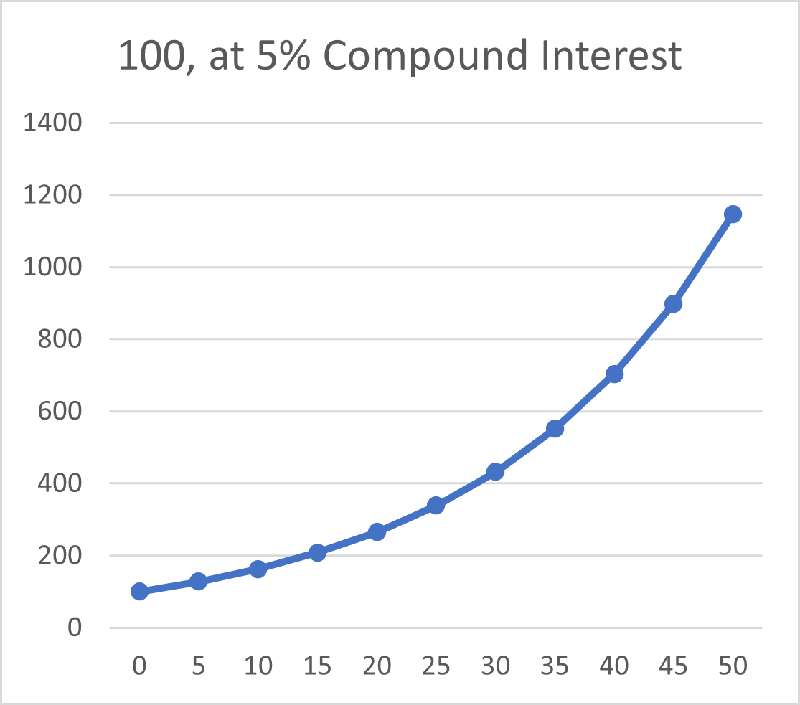
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what
Free checking is profitable three ways: the spread on your deposits, overdraft fees worth $5.8 billion in 2023, and interchange on every
BNPL looks free because the store pays the bill. Merchants pay 2-8% per transaction, late fees add millions, and longer Affirm loans carry
Cash advances charge interest from day one, with fees of 3-5% and APRs up to 29.99%. Why issuers skip the grace period, and what a $1,000
Compound interest means earning interest on your interest. See how rate, compounding frequency, and time shape your savings, with a worked
A credit card grace period is the interest-free window between your statement date and due date. Miss a full payment and you lose it on new
Your APR becomes a daily rate applied to your average daily balance every day. Follow the math with a worked $1,000 example
A 2% rewards card earns $200 on $10,000 of spending, but a $2,000 balance at 22% APR costs about $440 a year in interest. The math shows
A daily periodic rate is your APR divided by 365, applied to your average daily balance each day. Worked examples show exactly how
A high-yield savings account pays far more interest than a regular savings account. Learn how APY works, how the FDIC protects you, and how
A savings account paying 0.37 percent while prices rise 2.4 percent loses purchasing power yearly. The nominal-minus-inflation math
A $5,000 balance at 22% APR takes 19 years to clear on minimum payments, costing $8,100 in interest. Here is the math behind
Your savings rate tracks the Federal Reserve's benchmark more than your bank's mood. How FOMC decisions move APYs, why banks